
Changing Seasons
Fall always brings an appreciation of the changing season, and as we wrap up the mid-term elections, we also recognize and appreciate the freedom we have to choose. The choice of the candidates we support, the choice of the causes we donate to, the choice of our investments and portfolio allocation.
The third quarter brought a 2% return in the S&P 500, bringing the year-to-date return to 11.8%.* Artificial intelligence (AI) continued to drive the market, though there is growing concern over a possible AI bubble on the horizon. Potential disruptions in AI advancements could include a cyber security event, increased regulations, or unsupportive debt obligations from data center rollouts. We cannot predict if or when any of these will occur, which is why we continue to emphasize diversification rather than reliance on any single theme.
Inflation remains elevated, primarily due to higher energy prices. The war in Iran caused an initial disruption in the markets early this year, but the ongoing effects have mostly been felt in inflation. In September, the Fed raised rates by 0.25% and indicated an additional rate increase before the end of the year, though they held off before the mid-term elections.
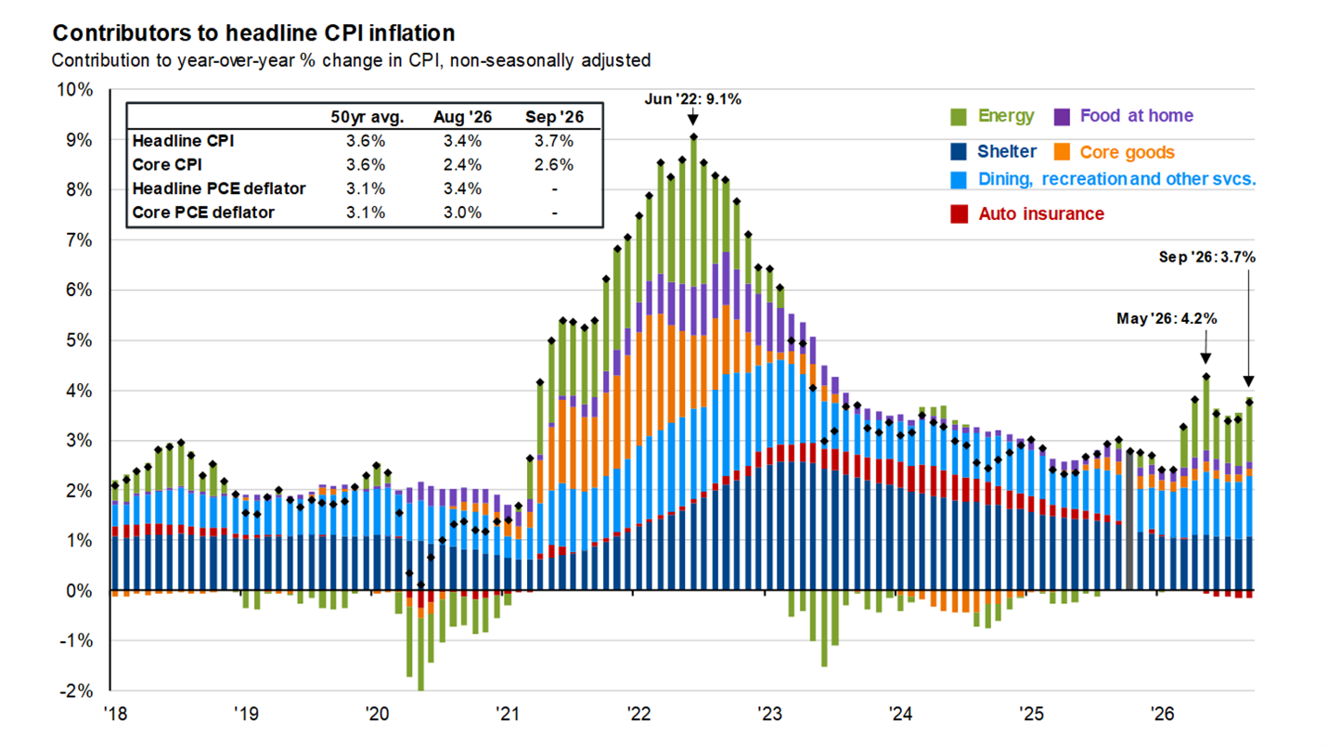
Source: JP Morgan Guide to the Markets, October 2026
As you can see from the chart above, inflation appears to be stable outside of the fluctuations we have seen this year in energy prices. Given the changing dynamics in inflation over the last several years, it is important to recognize the differences between energy driven inflation, and inflation caused by supply chain disruption or increased consumer demand. Typically, Fed policy changes will have limited impacts on energy prices, but since inflation excluding energy prices remains elevated above the Fed target of 2%, the recent rate adjustments seem appropriate.
Changes in the bond market have also been notable. Corporate bond issuance has increased due to investment in AI infrastructure and has led to upward pressure on bond yields. We saw bond values decline due to interest rate changes, but we continue to hear positive bond market outlook due to rising yields.
As we continue to consider the changes in the market and the economy, we remain committed to our investment philosophy and support of our clients and their families. We value your choice to work with us and look to the future with gratitude and grace to move through any challenges we may face. Our hope for the upcoming holiday season is that you find yourself surrounded by those that bring you joy and fulfillment. We welcome your thoughts and feedback, and we look forward to meeting with you again in the upcoming months.
Thomas L. Menzel, CFP® Laura Biermann, CFP®President Vice President
IMPORTANT DISCLOSURES: The opinions presented in this communication are subject to change without notice and no representation is made concerning actual future performance of the markets or economy. Information obtained from sources is considered reliable but is not verified. The research and other information provided herein speak only as of its date. We have not undertaken and will not undertake any duty to update the research or information or otherwise advise you of changes in the research or information. Performance information presented is not an indication of future results and index data is provided for market reference purposes only. This is not an offer to buy or sell or the solicitation of an offer to buy or sell any security/instrument or to participate in any particular trading strategy. This document is the property of Legacy Financial Advisors and is intended solely for the use of the Legacy client, individual, or entity to which is addressed. This document may not be reproduced in any manner or re-distributed by any means to any person without the express consent of Legacy. This material is for educational purposes only. Mis-transmission is not intended to waive confidentiality or privilege.